Ask French consumers about their budgetsthis year and the answer is mostly caution. Look a little closer, though, and adifferent picture comes into focus. Behind the careful average are shoppers whoare not only still spending, but planning to spend more, in some cases atlevels that rank among the highest in our study, and in categories where asingle decision can carry real value.
Our H2 Shopping Intent Study has alreadyshown that across eight markets, spending growth is concentrating rather thandisappearing (for the global picture, read Concentration, Not Contraction: Where Holiday Spending IsStill Growing). This article zooms in on France: who is stillspending, what is shaping their choices and where they are most open to hearingfrom brands.
Is France really a cautious market this year?
In short, yes, but not uniformly. Only onein four French consumers expects to spend more than last year, one of thelowest rates of the eight markets surveyed, while nearly half (48%) expect tospend less.1 Yet that figure hides a more balanced reality: morethan half (51.9%) plan to maintain or increase their spending.1French shoppers aren’t closing their wallets. They’re choosing more carefullywhere to open them.
Entertainment is a telling example. It isthe category French respondents choose most often, yet it is also the one wherethey are least likely to plan an increase, with only 15.1% expecting to spendmore.1 The interest is there; the extra budget isn’t. Caution alsovaries by age: women aged 50 and over are the most careful group in thecountry, with more than six in ten planning to cut back.1
For advertisers, the lesson is simple. InFrance, a plan built for the “average” shopper risks spreading budget acrosspeople who have already decided to hold back. The real opportunity sits withthree profiles.
Who are the French shoppers still spending?
The young premium man
Luxury and beauty are where French intentis strongest, and men are driving it. More than a third of French luxuryshoppers (35.2%) plan to spend more this year, above the luxury average acrossall eight markets (32.1%).1 Among men, that share climbs to 47.7%,almost twice the rate of women (25.4%), and 31.2% expect to spend a lot more.1Beauty, France’s second-strongest category with 29.3% planning to spend more,tells the same story: 35.2% of male beauty shoppers plan to increase theirbudget, against 25.7% of women.1 Even fashion and clothing, atougher category overall (22.5%), finds its growth among men (31.8% versus14.6%).1 The appetite shows in viewing habits too: in November andDecember 2025, beauty, fashion and luxury videos generated nearly 30 millionviews in France across Dailymotion and its partner sites.2
Age sharpens the picture. French consumersaged 18 to 34 are the most optimistic in the country, with 36.1% planning tospend more, twice the rate of those aged 50 and over (18.4%).1 Youngmen go further still: they are the only group in France where those planning toincrease their spending (43.9%) outnumber those planning to cut back (39.9%),and among young men shopping for luxury, 51% plan to spend more.1Creators help make the case: young men are the group most likely to use creatorpromo codes, and close to six in ten male luxury shoppers (58.8%) say creatorcontent concretely influences what they buy.1
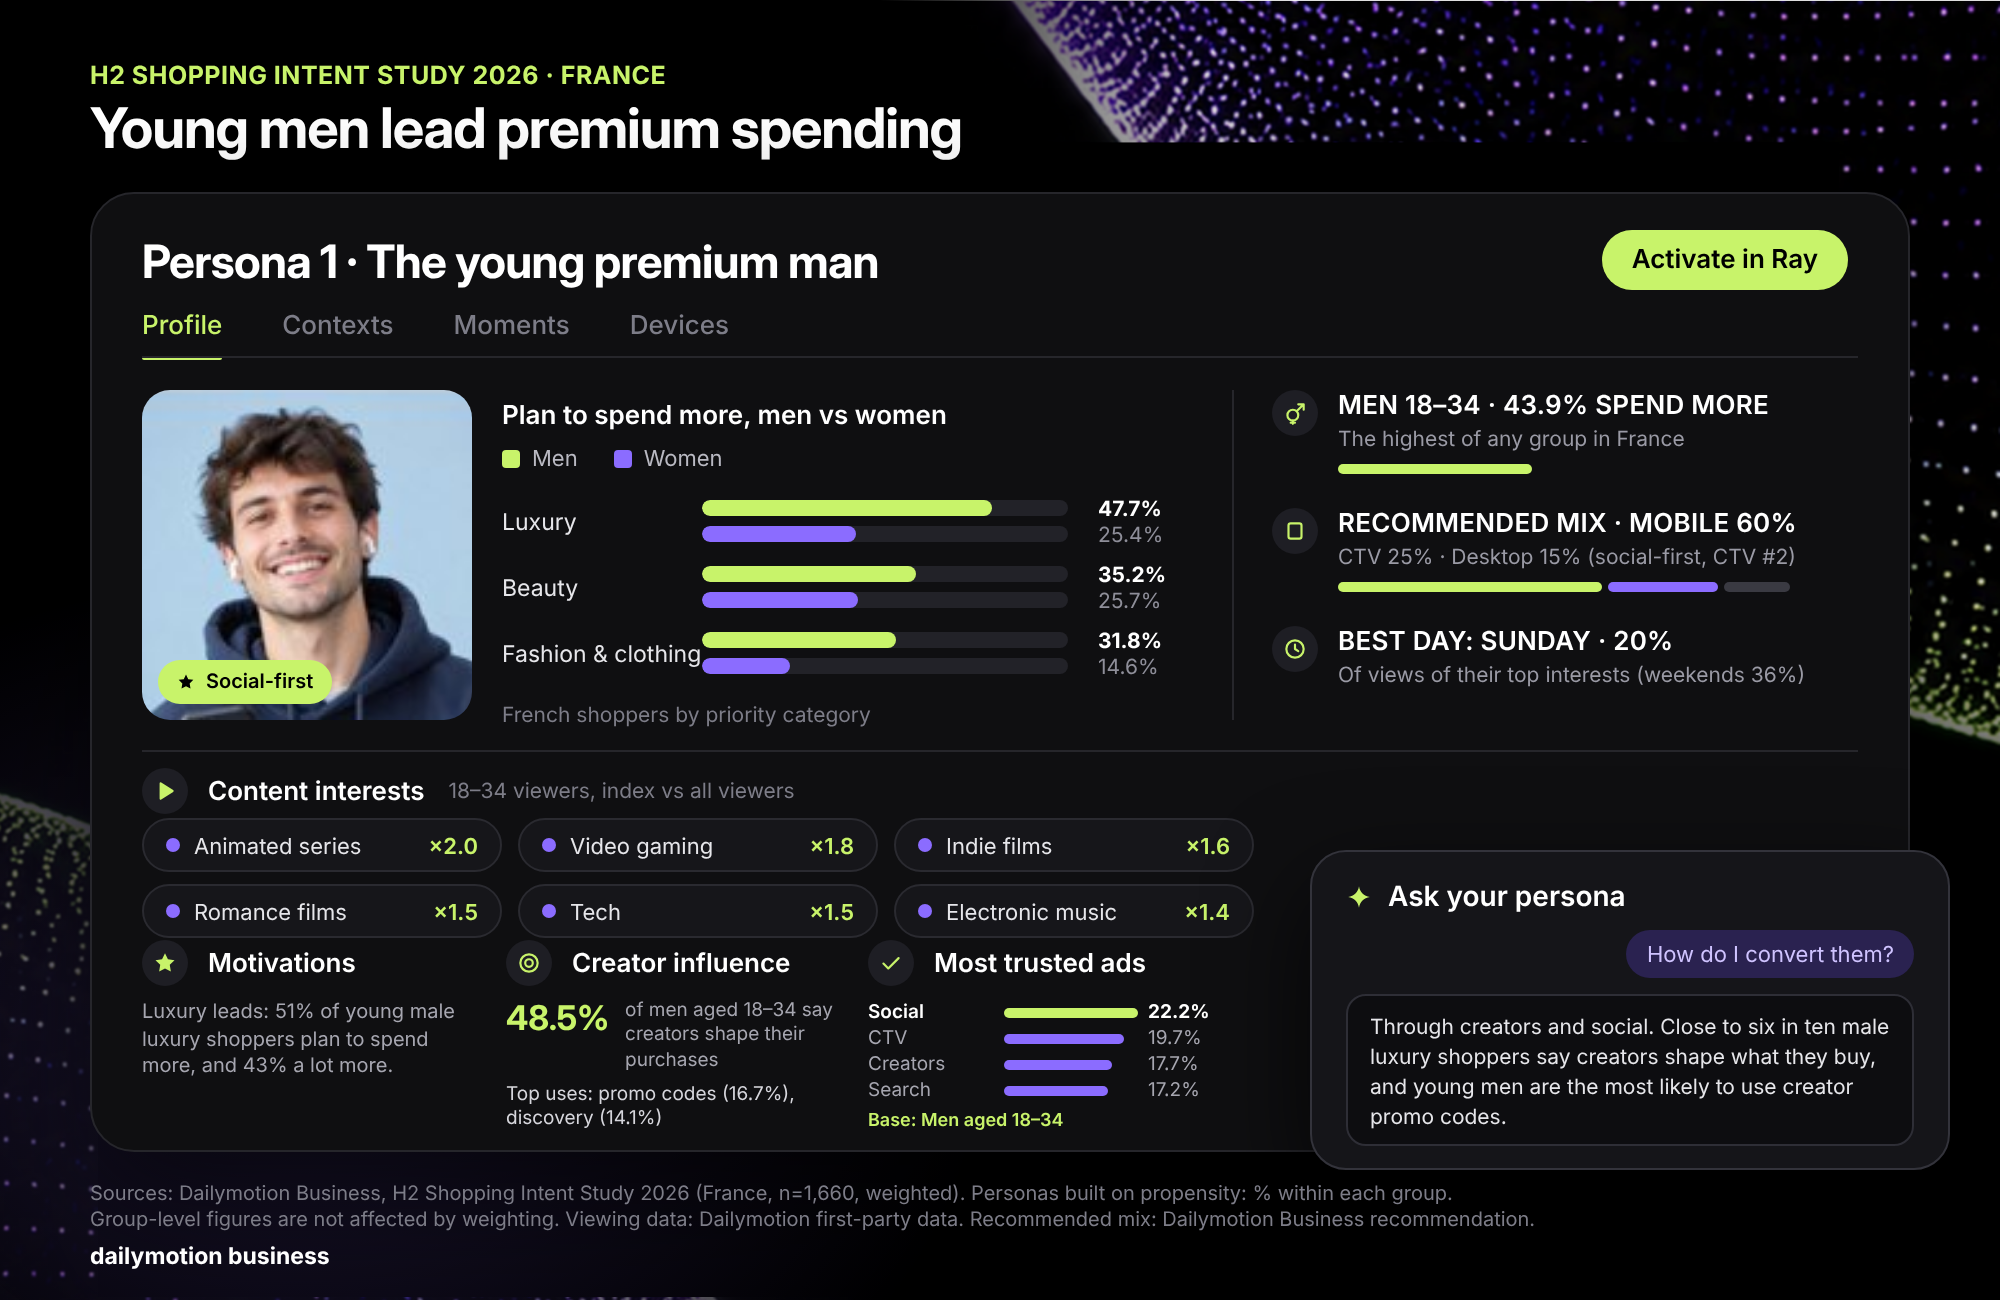
Persona 1: the young premium man. Source: Dailymotion Business, H2Shopping Intent Study 2026 (France) and Dailymotion first-party data.
The creator-guided planner
Where men lead on spending, women lead onguidance. French women are far more likely than men to say creator videos shapetheir purchases (51.8% versus 39.3%), and the gap is widest on thebiggest-ticket decisions.1 Among car buyers, 64.1% of women saycreators influence their choice, against 35.2% of men, and close to one in five(18.9%) use creator promo codes. Women are also more receptive than men to thechannels closest to creators: 20.5% name social as the advertising environmentthey trust most (versus 14.2% of men), and 15.3% name creator content (versus12.5%).1
Travel follows the same pattern, with 51.6%of women guided by creators, against 38.4% of men, and women travel shoppersare almost four times as likely as men to trust social ads most (26.0% versus7.0%).1 Even in beauty, where men plan to spend more, women remainthe more creator-led shoppers (55.5% versus 46.9%).1 These areplanned purchases: 27.7% of women prioritising travel and 27.4% of women carbuyers expect to spend more, slightly ahead of men. And the creator effectfollows the money: among French consumers planning to spend more, 54.6% saycreator video content plays a concrete role in their decisions, nine pointsmore than among those cutting back.1
That’s where Motion comes in. It helps brands identify thecreators, content and conversations that resonate with their audiences, buildcreator-led campaigns around those insights, and extend them beyond social intopremium video and CTV.
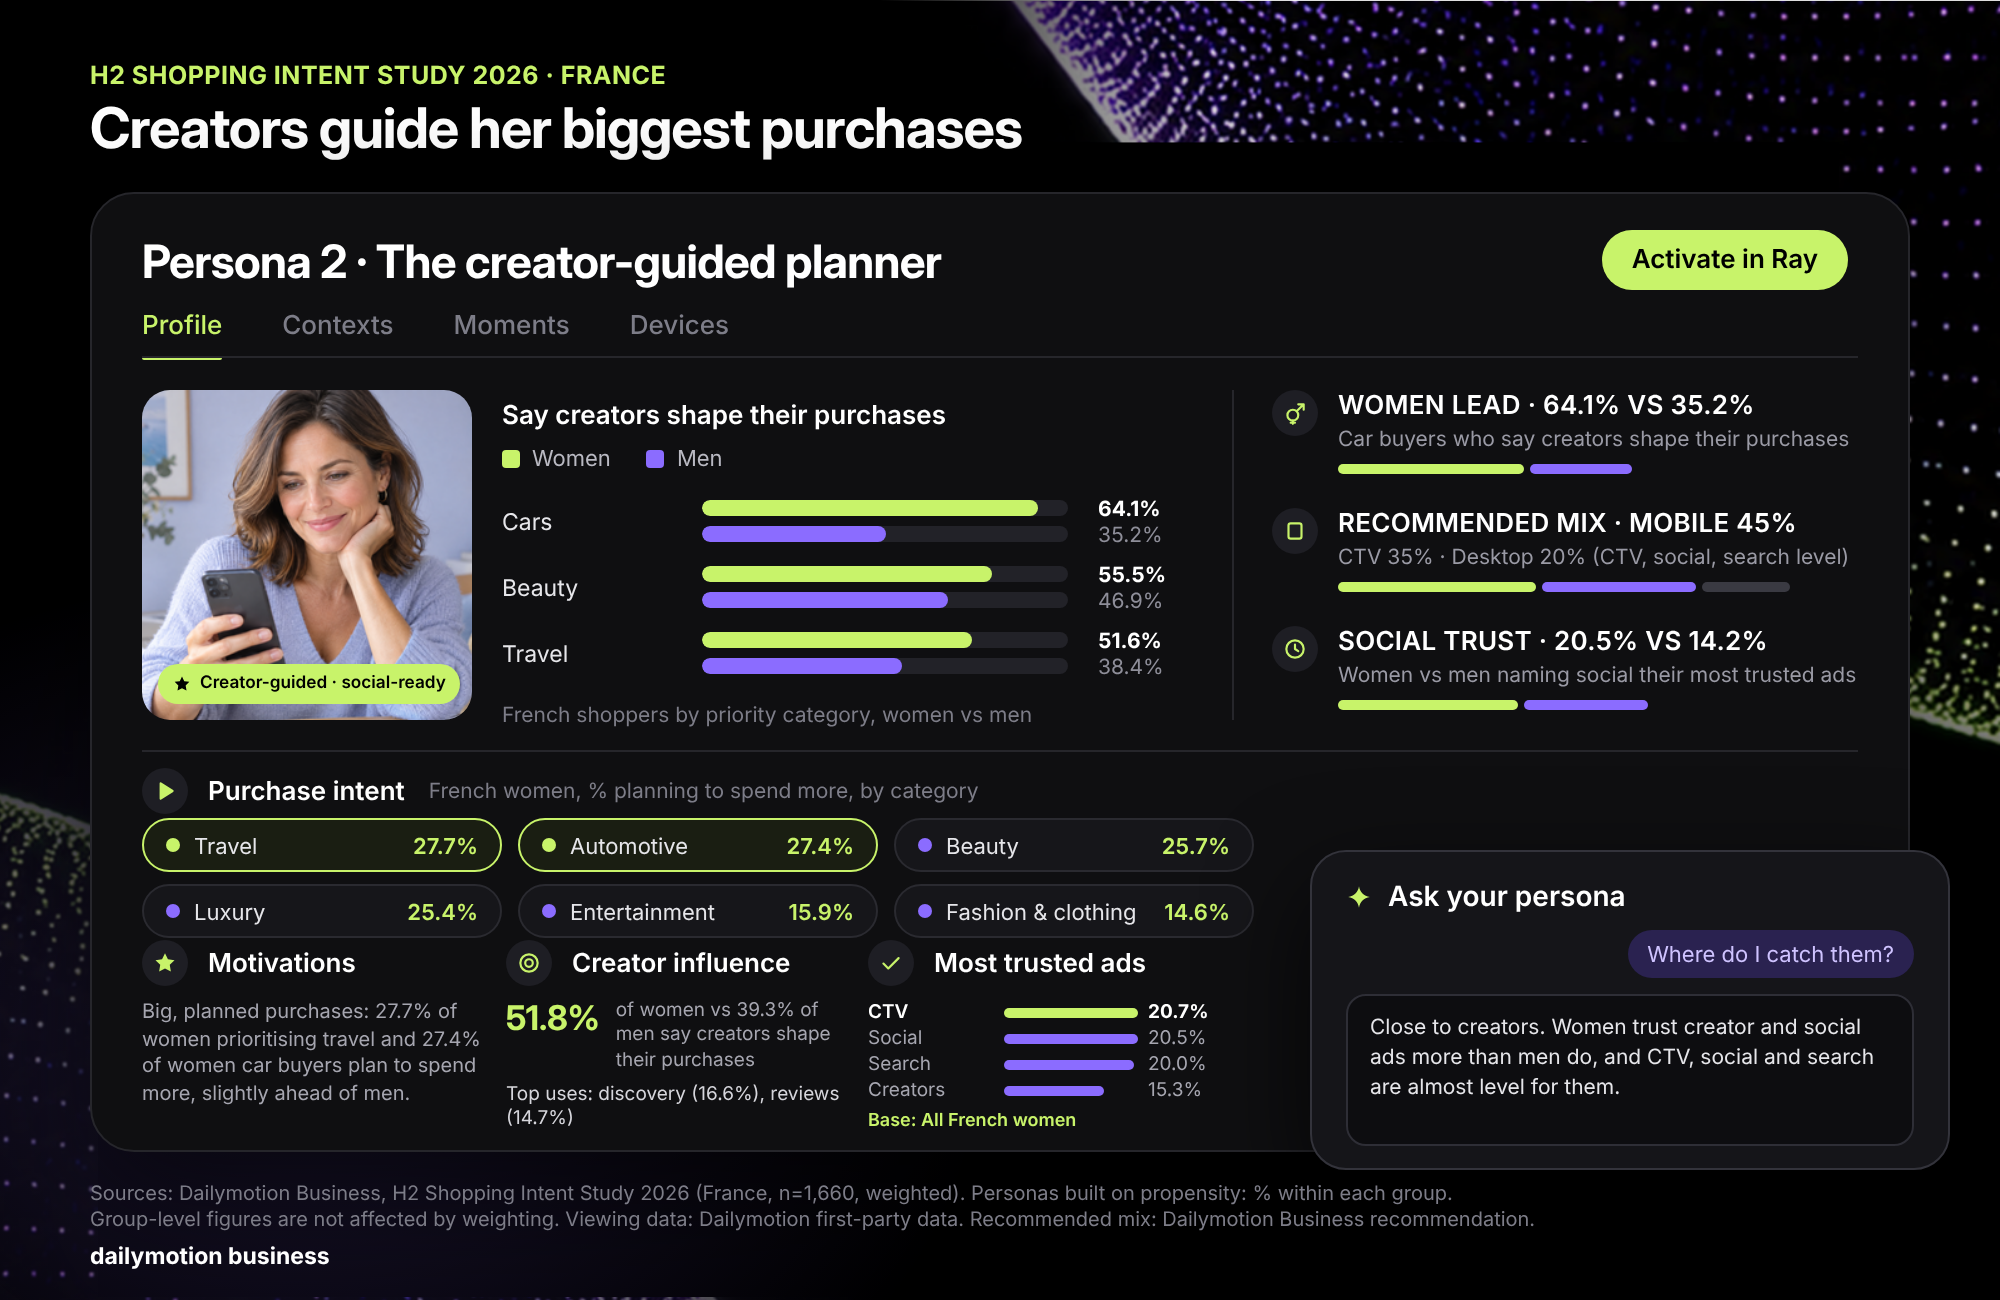
Persona 2: the creator-guided planner. Source: Dailymotion Business,H2 Shopping Intent Study 2026 (France) and Dailymotion first-party data.
The big-screen planner
The third profile is defined less by whatthey buy than by where they trust brands. French consumers aged 35 to 49 arethe most CTV-minded group in the country: 30.2% name connected TV as theadvertising environment they trust most, well ahead of search (19.0%) andsocial (18.6%), and above both younger (18.3%) and older shoppers (23.1%).1The pattern holds for men and women alike. Their budgets are steady rather thanshrinking: one in four (25.8%) plans to spend more, and half (50.0%) saycreators shape their purchases.
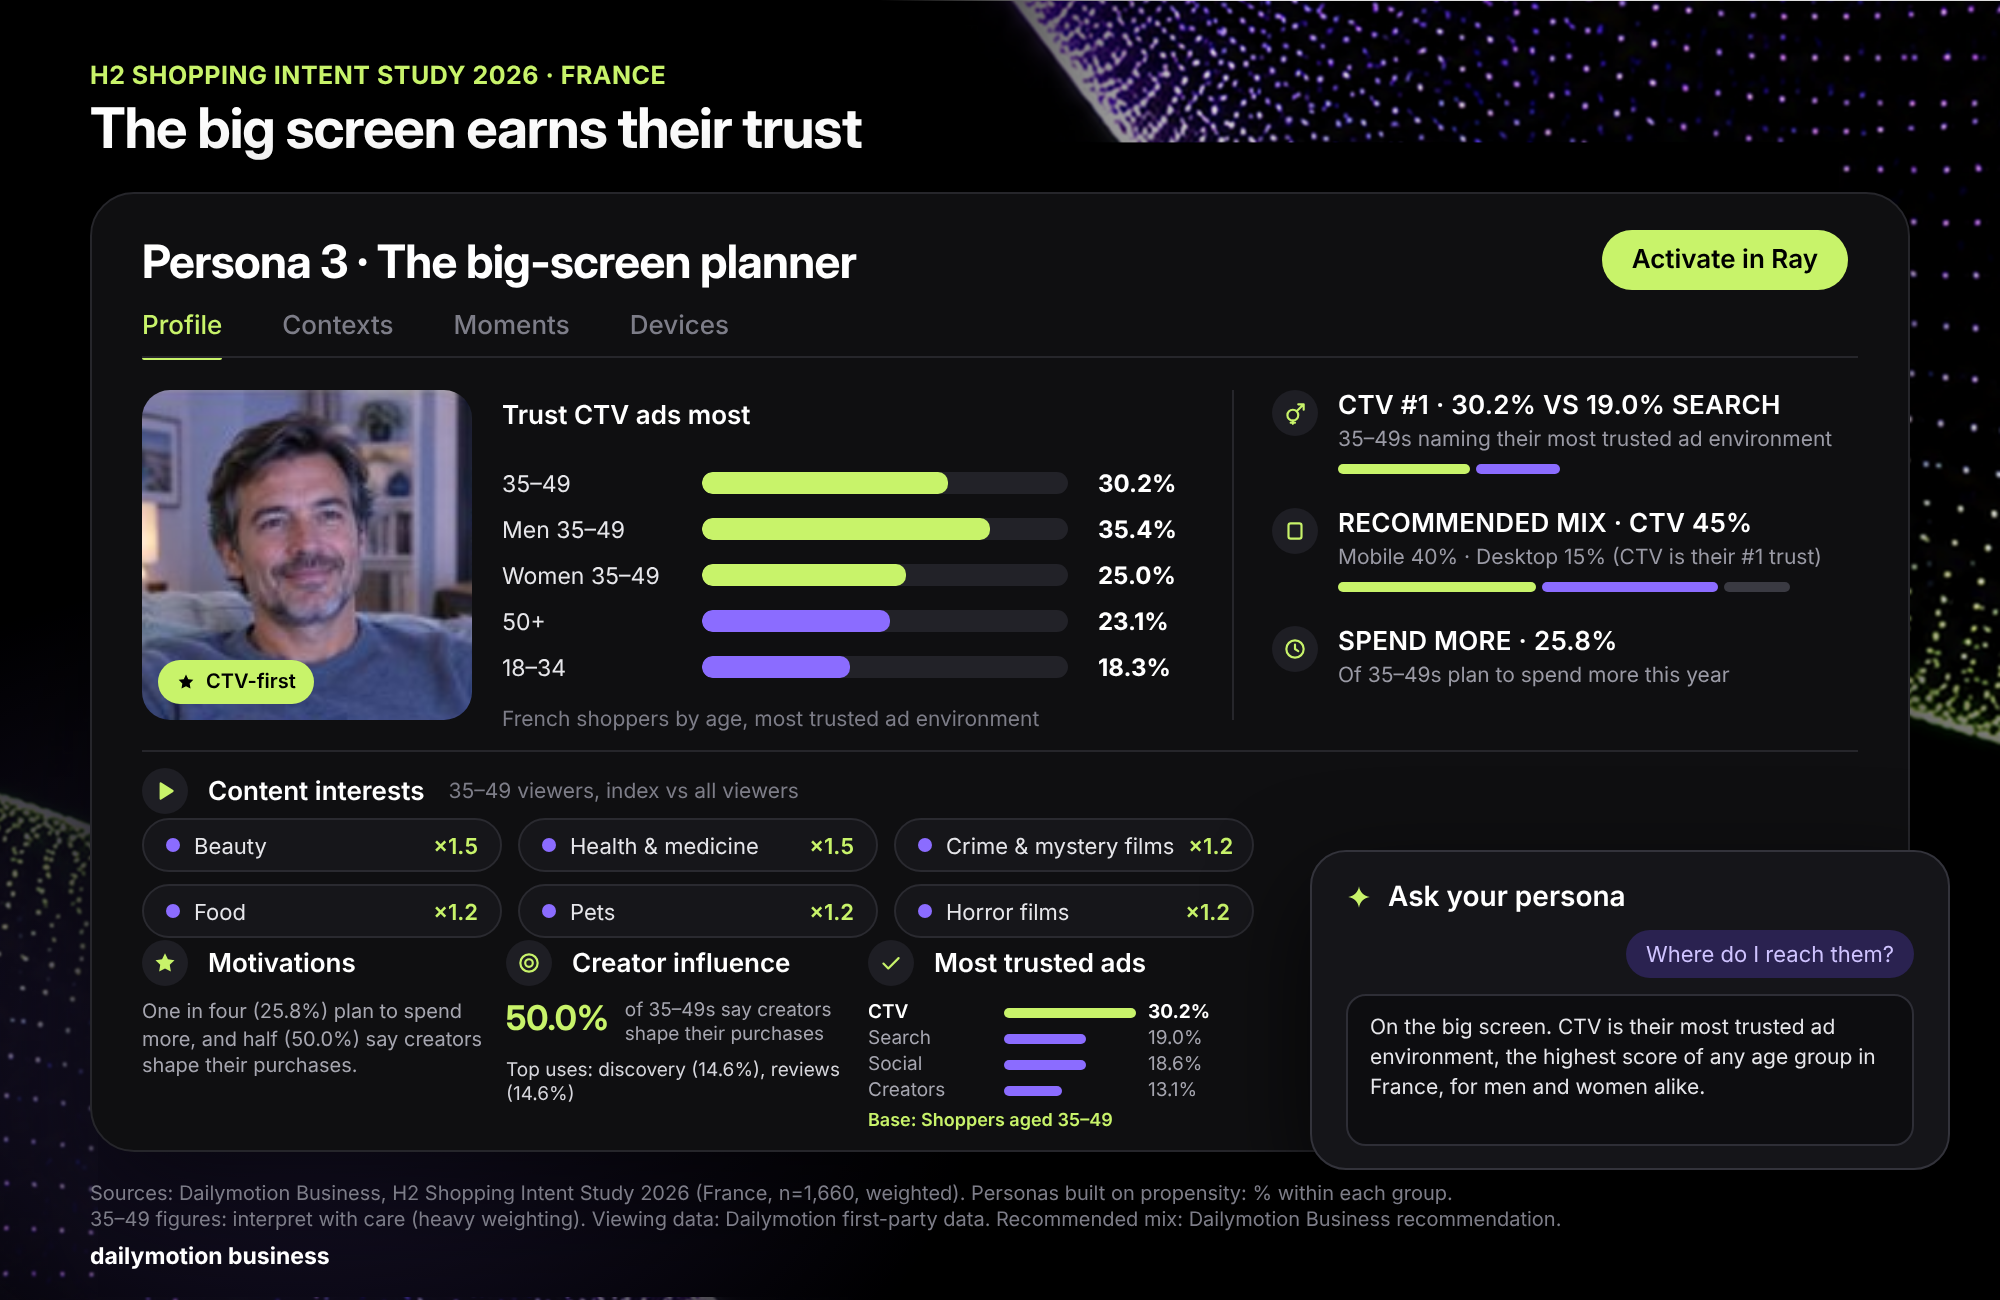
Persona 3: the big-screen planner. Source: Dailymotion Business, H2Shopping Intent Study 2026 (France) and Dailymotion first-party data.
Where do French shoppers trust brands most?
Reaching these shoppers is one thing;earning their attention is another. In France, the answer sits on the biggestscreen in the home. Connected TV is the advertising environment Frenchconsumers trust most, ahead of search and social, and France shows the highestlevel of CTV trust of the eight markets surveyed.1
That trust holds where it matters most forthe season. CTV also ranks first among French beauty (27.2%) and travelshoppers (28.6%). Compare France with the seven other markets and it leads onCTV trust in four categories: travel (28.6%), beauty (27.2%, more than fivepoints ahead of the UK), entertainment (26.1%) and luxury (23.4%).1When every screen fills up with promotions in the fourth quarter, a messagedelivered in a trusted environment carries more weight.
Dailymotion Business lets brands activateCTV through the Dailymotion app and across partner smart TV platforms such asTitan OS, VIDAA and TCL, including homescreen placements that put a brand onthe first screen viewers see when they turn on the TV, before they’ve evenchosen what to watch.
How do you reach French shoppers before they search?
In a selective market, the brands that winare often the ones that show up early, while a shopper is still exploringrather than comparing prices. Ray, Dailymotion’s agentic operating system,brings together audience, contextual, social, creator, consumption and campaignsignals from across the video ecosystem to understand not just who audiencesare, but what they watch and which interests are starting to shape their nextpurchase.
Powered by Ray, Audience Path turns those signals into futureshoppers, whether they’re browsing gift guides or exploring beauty, fashion ortravel content, and reaches them at the right time, in the right place and onthe right screen. Brands can activate these audiences alongside Motion’screator-led campaigns across French publishers such as Elle, Marie Claire,Paris Match, Le Monde and L’Équipe, buying directly or programmatically throughtheir preferred DSPs.
Your French Q4 checklist
· Plan for profiles, not averages.Prioritize young men in luxury and beauty, creator-guided women and 35–49 CTVviewers, where intent and trust are strongest.
· Let creators open the conversation. Theydrive young men’s luxury purchases and guide women’s biggest decisions, fromcars to travel.
· Use CTV for trust. Bring your strongestmessage to the screen French shoppers trust most.
· Start before the search. Catch intentwhile it’s forming, not once everyone is bidding for it.
France may look like a cautious market froma distance. Up close, it’s a market of clear choices, made by shoppers who knowwhat deserves their money this year. The brands that understand those choicesearly, and meet those shoppers where they trust brands most, are the ones thatwill make the list.
Readyto find your French shoppers? Let’sbuild your Q4 plan.
Notes
1. Dailymotion Business, H2 Shopping IntentStudy 2026 (Dailymotion, 2026), survey of 15,386 consumers in eight markets,including 1,660 in France, 23 July–11 Aug. 2026.
2. Dailymotion, “Views of Beauty andFashion Content in France, November–December 2025,” first-party audience data(Dailymotion, 2026).
In this article